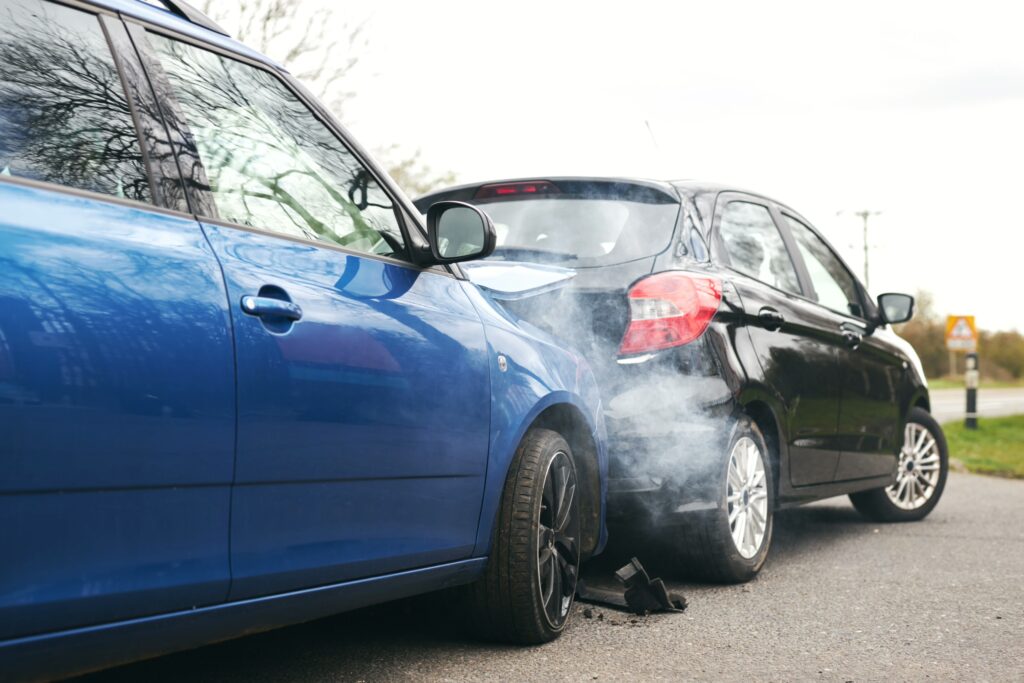
You were sitting at a red light on Brickell Avenue, minding your own business, when the impact hit. One second, everything was normal. Next, your head snapped forward and then back in a fraction of a second. The other driver pulls up behind you, both of you get out, look at the cars, and — honestly — it doesn’t look that bad. You tell him you’re okay. You drive home. You wake up the next morning barely able to turn your head.
That scene happens on Florida roads every single day. Rear-end collisions are among the most common crashes in the state, and whiplash is almost always what follows. But here’s the thing about whiplash — it’s one of the most misunderstood injuries in personal injury law. Insurance companies love to dismiss it, symptoms often don’t surface right away, and Florida has some very specific legal rules that can quietly kill your claim if you don’t know about them.
This article is for anyone who has been rear-ended in Florida and is trying to figure out what their options are. We’ll walk through what whiplash actually is, how Florida’s insurance laws affect your claim, when you can sue the driver who hit you, and what steps you need to take to protect yourself.
What Is Whiplash — and Why Doesn’t It Always Hurt Right Away?
Whiplash happens when your head gets thrown forward and then snapped back in rapid succession — the same cracking motion a whip makes. In a rear-end crash, your body gets pushed forward by the impact while your head momentarily lags behind, then whips in the opposite direction. That sudden force can stretch and tear the muscles, tendons, and ligaments in your neck and upper back. In more serious cases, it can damage nerves, bulge or rupture cervical discs, and affect the spine itself.
What makes whiplash so legally tricky is that it often doesn’t hurt right away. Your body floods with adrenaline after any crash, which can mask pain for hours — sometimes longer. A lot of people feel fine at the scene and genuinely mean it when they say so. Then they spend the next 48 hours slowly stiffening up, wondering why they didn’t say something sooner.
By the time the full set of symptoms sets in, some victims have already made a recorded statement to an insurance adjuster, accepted a check, or — most dangerously — missed a legal deadline they didn’t know existed. That’s why understanding the timeline matters as much as the injury itself.
The symptoms of whiplash aren’t always limited to neck pain. Depending on the severity of the impact, you might experience any of the following:
- Neck pain and stiffness, particularly when trying to rotate your head
- Headaches starting at the base of the skull
- Pain or aching in the shoulders, upper back, and arms
- Dizziness and unusual fatigue
- Blurred vision
- Numbness, tingling, or weakness in the arms or hands
- Trouble concentrating, memory issues, or mental fog — sometimes called whiplash-associated disorder
- Sleep problems and irritability that seem unrelated to the accident
For many people, these symptoms ease up within a few weeks with rest and physical therapy. For others, the injury becomes chronic — affecting their quality of life for months or years. The difference matters a great deal when it comes to the value of your claim.
Florida’s No-Fault System: Where Your First Claim Goes
Florida is a no-fault insurance state, which means that after a car accident, you generally file a claim with your own insurance policy — not the other driver’s. Every registered driver in Florida is required to carry Personal Injury Protection (PIP).
Under Florida Statute § 627.736, your PIP policy provides up to $10,000 in total benefits. That covers 80% of your reasonable medical expenses and 60% of your lost wages — but both draw from the same $10,000 pool. It’s not two separate pots of money. Once that limit is used up, it’s gone, regardless of how your treatment is going.
There’s an important wrinkle here. You only get access to the full $10,000 if your treating provider diagnoses you with what Florida law calls an “emergency medical condition.” If they don’t make that finding, your benefits are capped at $2,500. That gap — from $10,000 down to $2,500 — can be significant for someone dealing with ongoing whiplash treatment, which is another reason why the doctor you see first and what they document matters enormously.
The 14-Day Rule: The Deadline That Catches People Off Guard
Here is the rule that trips up more Florida accident victims than any other. Under Florida Statute § 627.736(1)(a), you must seek medical treatment within 14 days of your crash to qualify for any PIP benefits at all. Not some of them. All of them. Miss the window and your PIP coverage disappears entirely, with no exceptions for delayed symptoms, busy schedules, or simply not knowing the rule existed.
This creates a real problem for whiplash victims. Because symptoms often take a day or two to fully appear, people tell themselves they’re probably fine, put off the doctor visit, and before they know it two weeks have passed. At that point, an insurance company has no obligation to cover a single dollar of your medical bills under PIP.
The safest thing you can do after any rear-end crash in Florida is see a doctor the same day — or at the very latest within a few days. You can always be told there’s nothing wrong. But if you wait past 14 days and it turns out you are injured, there is no way to recover those PIP benefits.
One more thing worth knowing: if your PIP coverage runs out before your treatment is finished — which happens more often than people expect — you may still be able to pursue the at-fault driver’s bodily injury liability coverage for the remainder. That’s a conversation worth having with an attorney before you assume your options are limited to PIP.
Can You Actually Sue the Driver Who Rear-Ended You?
Florida’s no-fault system was designed to limit the number of lawsuits filed over minor accidents. As a result, simply having PIP coverage doesn’t automatically give you the right to sue the other driver directly. To do that, your injury has to meet a legal standard called the serious injury threshold.
Under Florida Statute § 627.737(2), you can sue the at-fault driver for pain and suffering, mental anguish, and other non-economic damages only if your injury falls into one of these categories:
- Significant and permanent loss of an important bodily function
- Permanent injury within a reasonable degree of medical probability (not counting scarring or disfigurement)
- Significant and permanent scarring or disfigurement
- Death
The threshold is harder to meet than it sounds. Whiplash that fully heals in a few weeks — even if it was painful — typically won’t qualify. But moderate to severe whiplash involving herniated discs, nerve damage, chronic restricted motion, or lasting pain almost certainly can. The statute’s operative word is “permanent,” which means your doctor’s opinions and documentation about the long-term nature of your condition will be the foundation of your case.
If your injury does clear the threshold, you can pursue the at-fault driver for everything PIP doesn’t cover: pain and suffering, loss of enjoyment of life, emotional distress, the portion of wages PIP didn’t replace, and future medical costs. That’s where a serious whiplash claim can translate into meaningful compensation.
What If the Insurance Company Says You Were Partly to Blame?
This comes up in many rear-end cases, even when the other driver clearly caused the crash. Insurance adjusters are paid to find reasons to reduce what they owe, and they may argue that you stopped too abruptly, had a brake light out, or made a sudden lane change. In most rear-end situations, the trailing driver is at fault — but “most” isn’t “always,” and even a partial fault finding can affect your payout.
Florida changed its rules on this in 2023. Under Florida Statute § 768.81(6), as amended by House Bill 837 and effective March 24, 2023, Florida now follows a modified comparative negligence standard. Here’s what that means practically: if you are found to be 50% or less at fault, you can still recover damages — but they will be reduced by your share of the blame. If you’re found to be 51% or more at fault, you recover nothing at all.
Under the old system, even a plaintiff who was 90% responsible for their own crash could still recover 10% of their damages from the other party. That’s no longer how Florida works. The shift is significant, and it’s one reason why building a well-documented, evidence-supported case matters more now than it did just a few years ago.
How Long Do You Have to File?
Florida’s 2023 tort reform also cut the filing deadline in half. For any accident that happened on or after March 24, 2023, you have two years from the date of the crash to file a personal injury lawsuit under Florida Statute § 95.11(4)(a). Before that law took effect, the deadline was four years. It’s now two.
Two years go faster than people expect, especially when you factor in medical treatment, recovery, trying to negotiate with an insurance company, and then realizing those negotiations aren’t going anywhere. Courts in Florida will dismiss a case filed after the deadline, regardless of how strong it is — and there’s generally no sympathy for not knowing about the deadline. The clock started on the day of your crash.
If your loved one was killed in a rear-end crash, the deadline for a wrongful death claim is also two years, running from the date of death rather than the date of the crash, under Florida Statute § 95.11(4)(d).
What You Should Do After a Rear-End Crash in Florida
The hours and days after a crash are when most people make the mistakes that hurt their case later. Here’s what to do — and what to avoid.
- Call 911 and file a police report. Even if the crash seems minor and both drivers are moving around fine, you want a police report. It creates an official record of what happened, identifies everyone involved, and documents any traffic violations. That report can be invaluable later.
- See a doctor within 14 days — the sooner the better. Go to an emergency room, an urgent care facility, or your own doctor. Tell them you were in a rear-end crash and describe every symptom you’re experiencing, even vague ones. Getting that initial visit on record protects your PIP rights and starts building your medical history.
- Stick with your treatment plan. If your doctor refers you to a specialist, go. If they prescribe physical therapy, attend every session. Insurance adjusters look for gaps in treatment as evidence that your injury wasn’t as serious as you claim. Consistency matters.
- Document everything you can. Photograph the vehicles, the road, any visible injuries, and the accident scene. Start keeping a simple daily log of your symptoms, pain levels, and how the injury is affecting your daily activities. Courts and juries respond to specific, detailed records.
- Don’t give a recorded statement to the other driver’s insurer. They will call you. They will be friendly. They will ask you to just “walk them through what happened.” You have no legal obligation to do this, and adjusters are specifically trained to use your words to minimize your claim. Politely decline until you’ve spoken with an attorney.
- Don’t accept the first settlement offer. Early offers are almost always low, and they come before the full extent of your injury is clear. Once you sign a release, that’s the end of your claim — permanently. Take your time and get proper advice first.
- Talk to a personal injury attorney. Florida’s PIP rules, the serious injury threshold, comparative fault, and the two-year deadline are all genuinely complicated. An attorney can tell you exactly where you stand, handle the insurance company on your behalf, and fight for what you’re actually owed.
What Is a Florida Whiplash Claim Actually Worth?
There’s no honest way to give you a dollar figure without knowing the details of your case. What we can tell you is that whiplash claims in Florida range from a few thousand dollars — for soft-tissue injuries that resolve quickly — to well into six figures for chronic, permanent cervical injuries that affect someone’s ability to work and function. The gap between those two ends is enormous, and the difference usually comes down to the quality of medical evidence.
The factors that most directly influence value include:
- How severe the injury is and whether it meets the “permanent” standard under § 627.737
- Total medical costs, including projected future treatment
- Lost income — both what’s already been lost and what may be lost going forward
- How clearly and consistently the injury is documented in medical records
- The degree of fault attributed to each driver
- The coverage limits of the at-fault driver’s insurance policy
One thing that consistently separates lower-value settlements from higher ones is the medical record. Juries and insurance adjusters alike respond to clear, detailed documentation of what happened to your body, how it was treated, and what the long-term outlook is. A whiplash injury that’s thoroughly documented by treating physicians, supported by imaging such as MRI results, and backed by a consistent treatment history will always be valued more fairly than one that isn’t.
Key Takeaways
- Whiplash symptoms are often delayed. Don’t assume you’re fine just because you felt okay at the scene.
- Florida’s 14-day rule (Fla. Stat. § 627.736) is a hard deadline — miss it, and you forfeit all PIP benefits, no exceptions.
- PIP provides up to $10,000 in combined benefits (80% of medical costs and 60% of lost wages from the same pool). If your injury doesn’t qualify as an emergency medical condition, benefits are capped at $2,500.
- To sue the at-fault driver for pain and suffering, your injury must meet the serious injury threshold under Fla. Stat. § 627.737 — typically meaning a permanent injury.
- Since March 24, 2023, you have only two years to file a personal injury lawsuit (Fla. Stat. § 95.11(4)(a)). The old four-year window is gone.
- Under Florida’s modified comparative negligence law (Fla. Stat. § 768.81), being found more than 50% at fault bars you from recovering anything at all.
- Never give a recorded statement to the other driver’s insurance company before consulting an attorney.
- The strength of your medical documentation has more influence on your claim’s value than almost anything else.
Frequently Asked Questions
Can I still have a serious injury claim if the crash was low-speed?
Yes, and this is one of the most common misconceptions insurance companies rely on. The speed of a crash does not determine the severity of an injury. Studies have shown that even impacts in the 8–15 mph range can generate enough force to injure the cervical spine. What matters legally is how your body was affected and how that’s documented — not how fast the other car was going when it hit you.
The other driver’s insurance company already called me with a settlement offer. What should I do?
Don’t agree to anything yet. Early settlement offers are almost always made before your injury has fully declared itself, and they are designed to close your claim cheaply and quickly. The moment you sign a release, that chapter is closed — no matter how much worse things get. Run the offer by a personal injury attorney first. You have nothing to lose by getting a second opinion, and potentially a great deal to gain.
I didn’t see a doctor within 14 days. Have I completely lost my ability to recover anything?
Losing PIP benefits is a real and serious consequence of missing the 14-day deadline, but it doesn’t necessarily end every option you have. If your injuries are severe enough to meet the serious injury threshold under Florida Statute § 627.737, you may still be able to pursue a direct claim against the at-fault driver, even without PIP coverage in play. The path gets harder, but it may not be closed entirely. Talk to an attorney as soon as possible.
I was a passenger in the car that got hit. Do I have a claim?
Absolutely. Passengers have the same legal rights as drivers in injury claims. You can file a PIP claim through the vehicle owner’s insurance policy, or your own if you have coverage. And if your injuries meet the serious injury threshold, you can pursue the at-fault driver directly, the same as anyone else involved in the crash.
How long does a whiplash case usually take to resolve in Florida?
It genuinely depends. A straightforward PIP claim for a relatively minor injury might be wrapped up in a few months. A case that involves litigation — where you’re actually filing a lawsuit and going through discovery — can take anywhere from one to three years, sometimes more. One thing worth keeping in mind: it’s generally better to wait until you’ve reached what doctors call “maximum medical improvement” before settling, so you have a clear picture of what your long-term costs are actually going to be.
Do I need a lawyer, or can I handle a whiplash claim on my own?
For a truly minor injury that heals quickly and for which PIP covers everything, handling it yourself may be manageable. But once you’re dealing with ongoing treatment, lost wages, questions about the serious injury threshold, or an insurance company that’s pushing back on your claim, having an attorney makes a real difference. Insurance companies have experienced adjusters and in-house counsel working these claims every day. Having someone who knows the system working on your side isn’t a luxury — it’s a practical necessity.
Hurt in a Rear-End Crash in Florida? Let’s Talk.
Whiplash gets dismissed a lot — by insurance companies, by people who’ve never experienced a serious one, sometimes even at the scene, by the very person who caused it. But a whiplash injury that doesn’t heal properly can follow you for years, affecting your ability to work, sleep, and do the things you care about. You deserve to have someone in your corner who takes it seriously.
At The Injury Claim Law Firm, we’ve worked with Florida accident victims long enough to know how insurance companies handle these claims — and what it takes to push back effectively. If you’ve been hurt in a rear-end crash, here’s what reaching out costs you:
- Nothing. Your initial case evaluation is completely free.
- No commitment. Talking to us doesn’t obligate you to hire us.
- No upfront fees. We work on a contingency basis — we only get paid if you do.
The two-year filing deadline started the day of your crash. The sooner you understand your options, the more of them you’ll have. Reach out to The Injury Claim Law Firm today.
Ready to talk about your case?
Contact The Injury Claim Law Firm — Your Free Consultation Is One Click Away.